


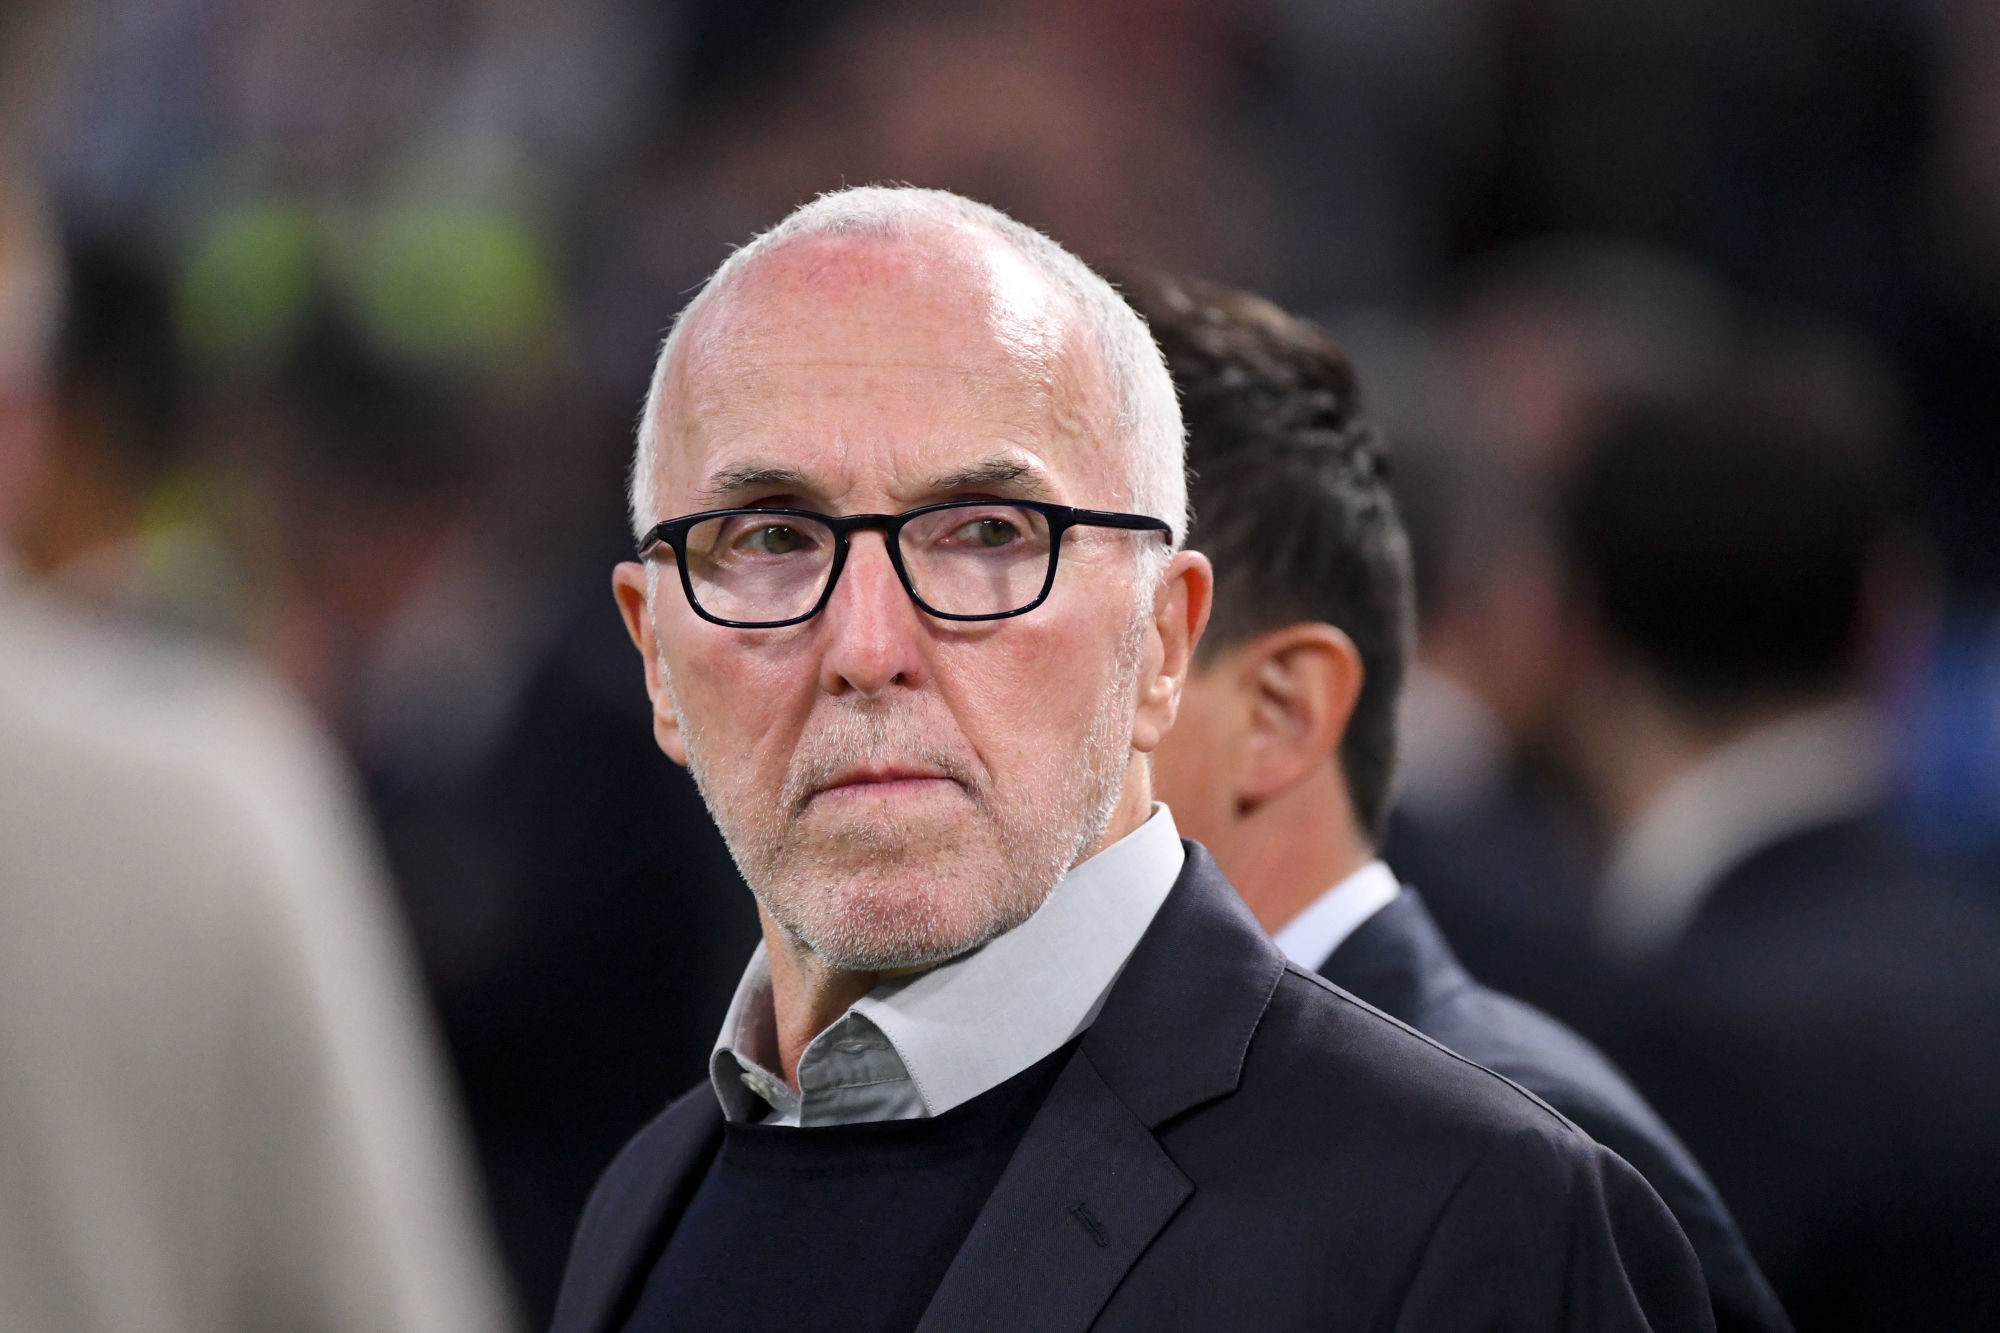
Marseille's Owner, Frank McCourt, Injects €50.2 Million into the Football Club
Marseille's Owner Injects €50.2 Million into the Football Club: A Strategic Move to Secure the...
An adjustable-rate mortgage, or ARM, can be a great option for homebuyers who are willing to take on some level of uncertainty in exchange for the possibility of securing a lower interest rate over the life of the loan. These types of mortgages can be particularly appealing to buyers who plan to rent out or flip an investment property or who know they will be moving within the initial fixed-rate period. Unlike fixed-rate mortgages, which offer the same interest rate for the entire loan term, ARMs offer a lower fixed rate for an initial period before adjusting to market rates.
According to the Mortgage Research Center, fixed-rate home loans account for around 92% of all mortgages in the U.S. However, with the current interest rate environment, some buyers are beginning to explore alternative options, such as ARMs. In fact, around 8% of borrowers opt for ARMs, despite their inherent risks and uncertainties.
The appeal of ARMs lies in their potential for saving borrowers money in the long run. While the initial fixed-rate period may be lower, the borrower can save thousands of dollars on interest payments. For example, consider a 10% interest rate on a 30-year fixed-rate mortgage versus a 4.5% interest rate on a 7/1 ARM during its initial fixed-rate period. While the ARM will adjust after the fixed-rate period, the borrower may still save thousands of dollars in interest payments.
That being said, ARMs are not without their risks. The borrower will face the possibility of increased monthly payments if the interest rate rises. Additionally, there is always the risk of unforeseen economic downturns, which could result in higher interest rates and even more significant payment increases. It is essential for buyers to carefully weigh the pros and cons before making a decision.
The type of ARM chosen can significantly impact the borrower's experience. For instance, a 5/1 ARM means the interest rate will remain fixed for the initial 5-year period before adjusting annually. In contrast, a 10/6 ARM offers a fixed rate for 10 years followed by adjustment periods every six months. Buyers must carefully consider these factors when comparing different ARM options.
One benefit of ARMs is that borrowers can refinance into a fixed-rate mortgage if their plans change. This is often the case for buyers who find themselves staying in their homes longer than initially planned. Much like refinancing from one fixed-rate loan to another, refinancing from an ARM to a fixed-rate loan involves shopping around with lenders, providing documentation, and paying off the existing mortgage.
The process of refinancing an ARM into a fixed-rate mortgage can be complex. Borrowers must weigh the potential risks and benefits before making a decision. A trusted loan officer can provide guidance and help determine if this is the right choice. With the current economy, some buyers may be opting for fixed-rate mortgages with higher interest rates in favor of the certainty and predictability they offer.
This market environment will undoubtedly continue to evolve in the coming months, and borrowers will need to be informed to make the right decision for their situation. ARMs may offer significant potential savings for borrowers, but the trade-offs must be carefully considered. Borrowers who weigh their options and make an informed decision will be best positioned to achieve their financial goals.
Current ARM mortgage rates report for Aug. 12, 2026 Fortune
Marseille's Owner Injects €50.2 Million into the Football Club: A Strategic Move to Secure the...
Rebel Creamery LLC, a major ice cream brand, has filed for Chapter 11 bankruptcy following a...
Major ice cream brand seeks Chapter 11 bankruptcy after lawsuit

Cristiano Ronaldo and Georgina Rodriguez's Divorce Plan Revealed Sports.Fr
Kalshi Promo Code TSNEWS: Get $25 Prediction Bonus for UFC 330 Fights sports.yahoo.com

Major ice cream manufacturer Rebel Creamery LLC, a popular brand sold in stores like Walmart and...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...