

Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru
ASML, the world's only manufacturer of extreme ultraviolet (EUV) lithography machines, is set to release its Q2 2026 earnings results. The company's EUV lithography machines are crucial for printing the circuits inside today's most advanced artificial intelligence chips. Wall Street anticipates Q2 earnings per share (EPS) of $7.94, a 75.4% increase from Q2 2025's EPS of $4.55, on revenues of $10.27 billion, which would be a 17.8% increase year-over-year. This growth is expected to be driven by the increasing demand for advanced AI chips. The company's EUV lithography machines are in high demand, and ASML has been working to increase its production capacity to meet this demand. As a result, the company's revenue is expected to continue growing in the coming quarters.
After-hours options traders are predicting an 8.36% move either direction from ASML's current stock price upon the results release, which is more than double the average move for the semiconductor equipment maker from past earnings results of 4%. ASML shares are currently changing hands at $1,808, which is up 65% for the year so far, but down 11% since the start of July in the face of questions related to AI capital expenditures sustainability, and other issues facing semiconductor equipment names. The company's stock has been volatile in recent months, with investors closely watching the company's earnings reports and guidance for any signs of slowing demand. Despite this volatility, ASML's long-term growth prospects remain strong, driven by the increasing demand for advanced AI chips. The company's EUV lithography machines are essential for the production of these chips, and ASML is well-positioned to benefit from this trend.
Today, the key question is not whether ASML will meet consensus, but whether management will raise full-year guidance for a third time. ASML reported first-quarter 2026 results on April 15, which included revenues of €8.76 billion ($10 billion), a 13% year-over-year increase, and net income of €2.84 billion, with a gross margin of 53%, which was within the top of guidance. Following these results, the company increased full-year 2026 revenue guidance to €36 billion to €40 billion from a previous range of €34 billion to €39 billion. CEO Christophe Fouquet noted at the time that chip demand exceeded supply, and customers were fast-tracking capacity expansion plans. The Q2 guidance ASML gave was €8.4 billion to €9.0 billion, with a gross margin of 51% to 52%. Zacks' consensus for Q2's revenue is $10.28 billion, and its EPS is $7.98. However, it doesn't matter if the results surpass these figures, as analysts have made it clear that the real catalyst is the outlook for Q3 and whether ASML increases full-year guidance for yet another time.
In recent weeks, several analysts have raised their price targets for ASML, citing the company's strong growth prospects and increasing demand for its EUV lithography machines. BofA analyst Didier Scemama raised his price target to $2,345 ahead of the earnings release and expects ASML's 2027 order book to be sold out by the time of the results. Should the order book be disclosed on the call, then the stock's focus would shift from the 2026 earnings results to its 2028 opportunity, which is a much larger figure than 2026. JPMorgan, which has an Overweight rating on the stock with a $2,200 price target, has said ASML needs to provide signals of capacity expansion and strong demand for 2027 and beyond for its stock to make new highs. Wells Fargo increased its target price to $2,200, from its $1,750 prior target, and believes semiconductor equipment names overall will deliver another strong quarter. The mean target of the eight analysts who rate ASML as a Buy is $2,119.67, which would give ASML 17% upside from current levels of $1,808.
ASML is currently in the middle of its $12 billion share repurchase program for the 2025 to 2028 period, and the company increased its dividend 17% earlier this year as well, both of which are signals of management's confidence in the company's ability to generate substantial cash flow in the future. The 11% pullback in ASML stock from its July peak would contradict the stock's surface narrative, which was a record results quarter. That decline was consistent with the pullback in the broader Philadelphia Semiconductor Index, which, after rising over 10% in the last month, fell as much as 16% from its record in June 22, only to eventually stabilize and close higher on that day. The underlying reason for the declines has been the concern that the artificial intelligence capital expenditure cycle that drove AI hyperscaler commitment on 2026 spending levels between $125 billion and $200 billion for Meta, Microsoft, Alphabet, and Amazon have pulled too much forward and left an air-pocket of slow orders in 2027 or 2028 for the semiconductor equipment makers.
ASML has been specifically impacted by two other issues that have added to its risk profile. First, is the exposure to China, which has historically been a large source of revenue for the company, but is now under the spotlight from the rapidly changing Chinese export policy environment that can severely curtail the DUV equipment sales. Second, is the slow ramp-up of its High-NA EUV tool sales to volume manufacturing, which is another source of growth for ASML, although not significant until the first tools were delivered in 2025. ASML's answer to both of these issues will likely be in today's Q2 revenue guidance and the outlook for Q3. If management raises its full-year guidance again for 2026, and the Q3 result exceeds the $10.34 billion consensus, then the concerns related to a peak-out period lose their footing for now. If ASML maintains its existing guidance and the Q3 result misses the consensus of $10.34 billion, then we could see ASML stock fall another 11% from $1,808 to the key support triangle near $1,707.
The fact that options traders have priced in an 8.36% move either direction from the current stock price means they have a clear 50/50 chance of which scenario plays out. On the 2H timeframe, the $1,808 price level in ASML has bounced off the lower trendline of a triangle pattern to reclaim the 50EMA ($1,785) and 200EMA ($1,783). RSI sits at 60, building momentum, but not yet overbought. Immediate horizontal resistance is at $1,813 (the triangle trendline). A breakout with a daily close above $1,813 sets up targets for $1,860, $1,903, and then $1,942. An inability to break above $1,813 in the face of a very strong Q2 report would be a technical negative warning. A close back below the 50EMA support level at $1,785 exposes $1,760 and the 50-day trendline at $1,707.
Looking ahead, ASML's growth prospects remain strong, driven by the increasing demand for advanced AI chips. The company's EUV lithography machines are essential for the production of these chips, and ASML is well-positioned to benefit from this trend. However, the company also faces several challenges, including the risk of a peak-out period in AI capital expenditures and the impact of Chinese export restrictions on its business. Despite these challenges, ASML's long-term growth prospects remain strong, and the company is expected to continue to generate substantial cash flow in the future. As a result, ASML's stock is expected to remain a key player in the semiconductor equipment market, and investors will be closely watching the company's earnings reports and guidance for any signs of slowing demand or increased competition.
In conclusion, ASML's Q2 2026 earnings report is expected to be a key catalyst for the company's stock, with investors closely watching the company's revenue guidance and outlook for Q3. The company's growth prospects remain strong, driven by the increasing demand for advanced AI chips, and ASML is well-positioned to benefit from this trend. However, the company also faces several challenges, including the risk of a peak-out period in AI capital expenditures and the impact of Chinese export restrictions on its business. As a result, investors will be closely watching ASML's earnings reports and guidance for any signs of slowing demand or increased competition, and the company's stock is expected to remain a key player in the semiconductor equipment market.
ASML's future growth prospects are closely tied to the demand for advanced AI chips, and the company's ability to meet this demand will be a key factor in determining its success. The company's EUV lithography machines are essential for the production of these chips, and ASML is well-positioned to benefit from this trend. However, the company also faces several challenges, including the risk of a peak-out period in AI capital expenditures and the impact of Chinese export restrictions on its business. Despite these challenges, ASML's long-term growth prospects remain strong, and the company is expected to continue to generate substantial cash flow in the future. As a result, ASML's stock is expected to remain a key player in the semiconductor equipment market, and investors will be closely watching the company's earnings reports and guidance for any signs of slowing demand or increased competition.
Overall, ASML's Q2 2026 earnings report is expected to be a key catalyst for the company's stock, with investors closely watching the company's revenue guidance and outlook for Q3. The company's growth prospects remain strong, driven by the increasing demand for advanced AI chips, and ASML is well-positioned to benefit from this trend. However, the company also faces several challenges, including the risk of a peak-out period in AI capital expenditures and the impact of Chinese export restrictions on its business. As a result, investors will be closely watching ASML's earnings reports and guidance for any signs of slowing demand or increased competition, and the company's stock is expected to remain a key player in the semiconductor equipment market.
ASML reports Q2 2026 earnings, with consensus expecting EPS of $7.94 and revenue of $10.27 billion, amidst concerns over AI capital expenditure sustainability and Chinese export restrictions
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru

Acara 600 ribu porsi kulinier gratis di Monas, menghidupkan semangat kebangsaan dan memperkuat rasa...
Hayden Panettiere, bintang televisi Amerika yang terkenal dengan perannya dalam serial 'Heroes' dan...
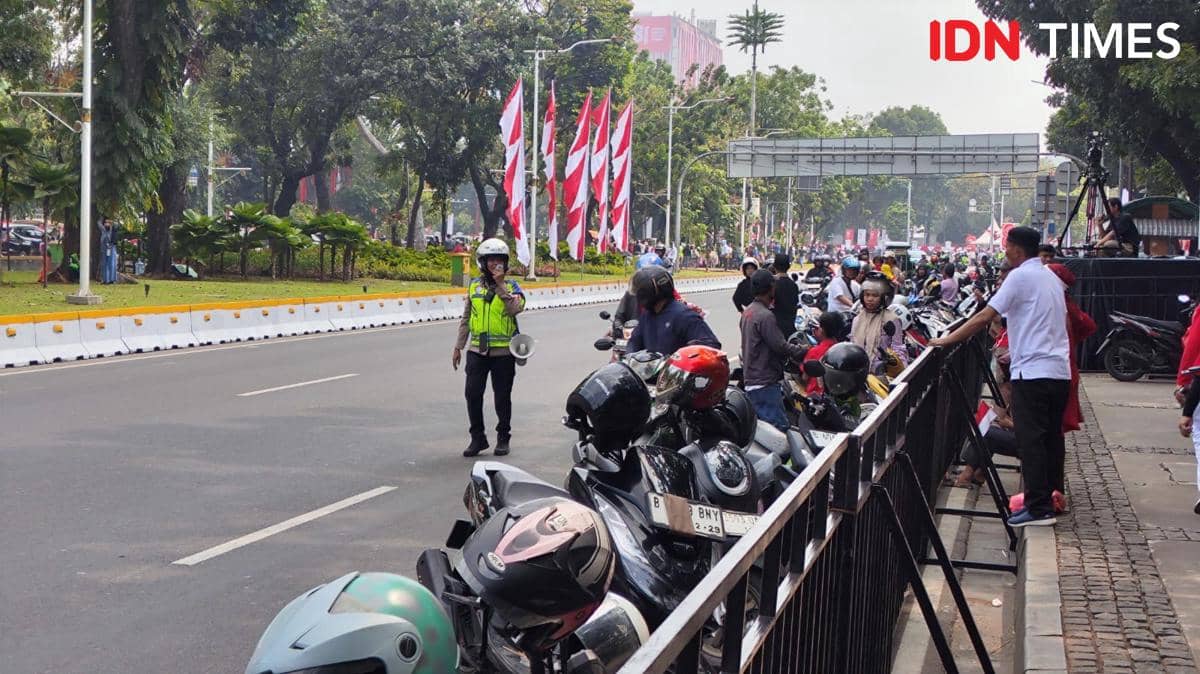
Jalan Merdeka Barat Dekat Istana Merdeka Jadi Parkir Liar Warga yang ke Monumen Nasional IDN Times

Kopassus Mengudara: Aksi Terjun Payung Terunggul di Istana Merdeka - Media Indonesia
Watch the live action of Tijuana vs. Cruz Azul, all the latest news, analysis, and match scores...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...