
Hawaii Emergency Update: Tropical Storm Lala Threatens Islands
Stay informed about Tropical Storm Lala's impact on Hawaii, with updates on warnings, advisories,...
This article was paid for by Intuit Credit Karma. Our editorial team independently wrote this article. When you click on or buy through our links, we earn a commission. Learn more.
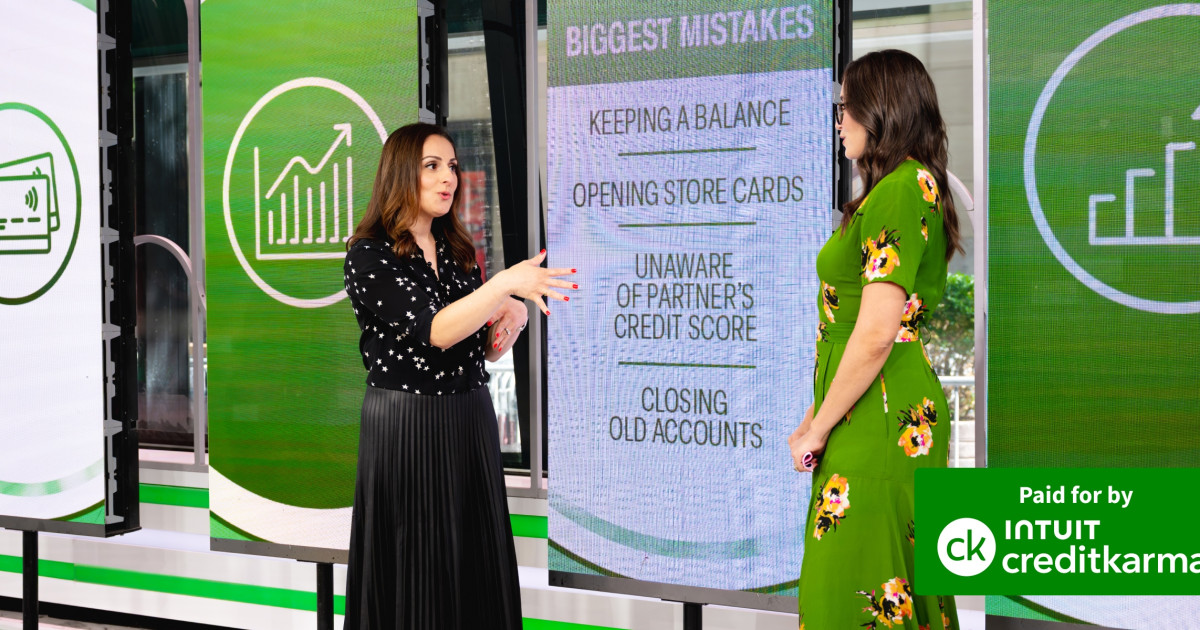
For this edition of On the Money, paid for by Intuit Credit Karma, personal finance expert and host of the "So Money" podcast Farnoosh Torabi stopped by TODAY to share what actually matters when it comes to credit scores.
One of the very first "money lessons" I remember learning about credit turned out to be completely wrong. As a young adult, a relative told me that carrying a balance on my credit card would actually help my credit score. The thinking was that lenders wanted to see I was using my available credit. But the reality is that there's a big difference between "using" credit and using it responsibly. Credit scoring models want to see that you're reliable, which means that you borrow money and consistently pay it back on time. In good practice, that doesn't mean carrying a balance from month to month. It means paying off your credit card statement in full each month, one of the healthiest habits you can build. For instance, paying your credit card bill in full every month can help you avoid interest charges, reduce your debt, and improve your credit utilization ratio.
That experience made something very clear: Credit can feel incredibly confusing, and misinformation too often gets passed from one generation to the next. Whether you're applying for your first credit card, shopping for a mortgage or simply trying to improve your financial health, understanding how credit works can save you money and open doors. With the average American having about six credit cards in their wallet, it's no wonder that credit can be overwhelming. In fact, according to a survey by the Credit Counseling Foundation, 62% of Americans don't understand how credit scores are determined. But understanding how credit works can have a significant impact on your financial life. By paying your bills on time, keeping credit utilization low, and monitoring your credit report, you can build a strong credit history and qualify for better loan rates and credit card offers.
Here's what everyone should know about credit, how your credit score is calculated and the simple habits that can help improve it. At its simplest, credit is a financial tool that lets you buy something today and pay for it over time. Whether you're swiping a credit card for a new laptop, taking out a student loan for college, or getting a mortgage to buy a home, you're borrowing money now with the agreement that you'll pay it back later. That's where your credit score comes in. Think of your credit score as an SAT score for your borrowing habits. It's a number — typically between 300 and 850 — that measures your credibility or trustworthiness as a borrower. This score is important because whenever you apply for a credit card, a loan or a mortgage, lenders and financial institutions will review this score to determine if you're eligible and what type of interest rate and terms to attach to your credit card or loan.
The higher the number, the better. In general, borrowers with scores in the high 700s and above qualify for the best interest rates. But, credit scores aren't the only factor lenders consider when making loan decisions. Other factors, such as your income, employment history, and loan payment history, also play a significant role. The good news is that improving your credit usually doesn't require anything dramatic. It's mostly about consistency. By making on-time payments, keeping credit utilization low, and monitoring your credit report, you can build a strong credit history over time. And, no, checking your own credit score does not hurt your credit. This is a widespread myth that has been debunked by credit experts. In fact, checking your credit score regularly can actually help you identify errors or inaccuracies on your report and dispute them before they affect your credit score.
So, what can you do to improve your credit score? Here are a few simple tips: 1) Pay your bills on time, every time. Payment history accounts for 35% of your credit score, so making on-time payments is crucial. 2) Keep credit utilization low. Aim to keep your credit utilization ratio below 30% for all credit accounts. 3) Monitor your credit report. Check your credit report regularly to ensure it's accurate and up-to-date. 4) Don't open too many credit accounts at once. Applying for multiple credit cards or loans in a short period can negatively affect your credit score. And, 5) Avoid negative marks on your credit report, such as collections or late payments. By following these tips, you can build a strong credit history and qualify for better loan rates and credit card offers.
And, lastly, checking your credit score often and knowing how it's changing over time is so important. Our sponsor Credit Karma has an app that can help you track your score and spot any red flags so you can fix them. By staying on top of your credit score and making small changes to your credit habits, you can achieve long-term financial success.
Our team features a range of qualified experts and contributors in our broadcast segments to reveal the latest in trends, remarkable sale events and all things shopping across a variety of categories.
Farnoosh Torabi is a personal finance expert, bestselling author and host of the award-winning podcast, "So Money."
Credit Score 101: Expert Tips — and Common Mistakes to Avoid TODAY.com
Stay informed about Tropical Storm Lala's impact on Hawaii, with updates on warnings, advisories,...
Marseille's Owner Injects €50.2 Million into the Football Club: A Strategic Move to Secure the...
Get an exclusive look at Elon Musk's vast SpaceX empire, a multibillion-dollar behemoth quietly...
Rebel Creamery LLC, a major ice cream brand, has filed for Chapter 11 bankruptcy following a...
Major ice cream brand seeks Chapter 11 bankruptcy after lawsuit

The ice cream industry has been shaken by the news of Rebel Creamery, a major ice cream brand sold...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...