


Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru
Taiwan Semiconductor Manufacturing Company, or TSMC, remains the indispensable cornerstone of the global technology sector, particularly as the artificial intelligence (AI) revolution accelerates. The company controls an astonishing 70% of global foundry revenue and over 90% of the world's most advanced chip production at leading-edge nodes like 3nm and 5nm. This near-monopoly isn't just a market share statistic; it's the very foundation upon which the AI infrastructure boom is being built, powering everything from advanced data centers to the latest smartphones.
TSMC's recent financial performance serves as a powerful testament to this dominance. The company reported a record-breaking first quarter in 2026, with revenue surging 35% year-over-year to $35.9 billion (NT$1.134 trillion). This impressive growth wasn't a fluke; it marked TSMC's fourth consecutive quarter of record profit, driven almost entirely by the insatiable demand for AI and high-performance computing (HPC) applications. Analysts and industry experts widely attribute TSMC's success to its strategic partnership with leading-edge innovators like Apple, Nvidia, and AMD, who value TSMC's cutting-edge chip production capabilities.
The numbers speak for themselves: HPC accounted for 61% of TSMC's Q1 revenue, while advanced chips (7nm or smaller) made up 74% of total wafer revenue, with 3nm nodes alone contributing 25%. This shift from consumer electronics to AI-driven computing is a structural change, not a cyclical blip. Hyperscalers like Nvidia, Apple, and AMD are all fiercely competing for TSMC's advanced node capacity, creating a supply-constrained environment that grants TSMC significant pricing power and robust margins. As C.C. Wei, TSMC's CEO, noted, "We are committed to meeting the increasing demand for AI chips, and our investment in advanced nodes will continue to drive growth and innovation in the industry."
This sustained demand has fueled a remarkable run for TSMC shares, which have more than doubled in the past year. The market's conviction in the multi-year AI megatrend is clear, and TSMC stands at its epicenter, validating that AI infrastructure spending is a production-scale commitment, not just speculative hype. While some analysts have raised concerns about TSMC's dependence on a few large customers, experts point out that the company's diversified revenue streams and its strong relationships with leading-edge innovators make it less vulnerable to market fluctuations. Furthermore, the AI boom is expected to drive strong demand for TSMC's advanced chips for the foreseeable future, ensuring its position as the undisputed leader in AI chip production.
TSMC's Q1 2026 earnings call delivered a resounding message: the AI infrastructure boom is not just real, it's accelerating, and TSMC is reaping the rewards. The company's net income surged a remarkable 58% year-over-year, reaching a record NT$572.48 billion. This profit jump, alongside a revenue increase of 40.6% year-on-year to $35.9 billion, comfortably surpassed both internal guidance and analyst expectations. C.C. Wei emphasized that "AI-related demand continues to be extremely robust," reinforcing the company's "conviction in the multi-year AI megatrend."
The key driver behind this stellar performance was the relentless demand for AI chips. TSMC has been working closely with its customers to meet this increasing demand, investing heavily in advanced node production and expanding its manufacturing capacity. As a result, the company has been able to take advantage of its unique position in the supply chain and drive significant growth through pricing power and volume. For example, the company's 3nm node is being used by leading-edge innovators like Apple and Nvidia, with TSMC expecting the high-growth demand to continue in the coming years.
Despite the AI boom, concerns abound about the sustainability of TSMC's growth trajectory. The company operates almost entirely from Taiwan, which is situated near China, making it an attractive target for geopolitical risks. As tensions between the US and China continue to escalate, the risk of a Taiwan conflict remains a major concern for investors. However, TSMC CEO C.C. Wei has consistently emphasized that Taiwan will remain the core of the company's R&D and its most advanced production. The company's diversified revenue streams and its strong relationships with leading-edge innovators mitigate some of this risk.
TSMC is investing heavily in overseas fabs, with major projects underway in Arizona (USA), Kumamoto (Japan), and Dresden (Germany). The first Arizona fab, focused on 4nm technology, is slated to begin production in early 2025, with a second fab for 2nm targeted for 2030. In Japan, a second fab is also under construction, and a new facility in Dresden, Germany, marks its first European expansion. These efforts are partly in response to government incentives, such as the U.S. CHIPS and Science Act and the EU Chips Act, which aim to onshore critical chip capacity. However, replicating TSMC's scale, technological expertise, and deeply integrated supply chain outside of Taiwan presents immense hurdles.
The company's current valuation presents a complex picture, reflecting both its unparalleled technological leadership and the significant geopolitical overhang. The stock is trading at $414.15 as of May 7, 2026, near its 52-week high of $420.00, and boasts a colossal market capitalization of $2.15 trillion. This premium valuation is largely driven by its indispensable role in the AI boom and its robust financial performance. Looking at key valuation multiples, TSMC trades at a TTM P/E of 30.85, a P/S of 14.50, and a P/FCF of 58.49. While these metrics appear elevated compared to historical averages for some industrial sectors, they are arguably justified by the company's exceptional growth profile.
Wall Street analysts generally maintain a bullish stance on TSM. The consensus price target is $427.50, with a median of $450.00 and a high of $480.00, suggesting further upside from current levels. Out of 25 analysts, 18 rate it a "Buy" and 7 a "Hold," with no "Sell" ratings. This optimism largely stems from the "unbreakable supply chain momentum" fueled by AI and the company's strong pricing power due to capacity constraints.
Is TSMC Still the Unbeatable Leader in AI Chip Production? Kavout | AI
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru

Acara 600 ribu porsi kulinier gratis di Monas, menghidupkan semangat kebangsaan dan memperkuat rasa...
Hayden Panettiere, bintang televisi Amerika yang terkenal dengan perannya dalam serial 'Heroes' dan...
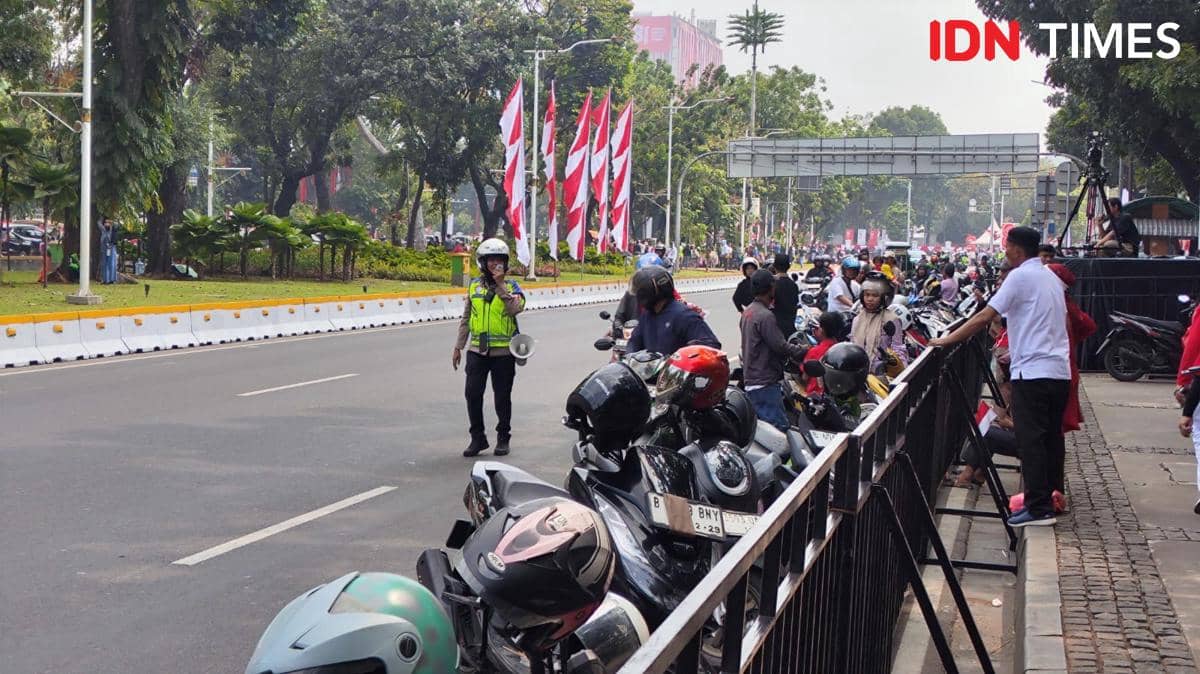
Jalan Merdeka Barat Dekat Istana Merdeka Jadi Parkir Liar Warga yang ke Monumen Nasional IDN Times

Kopassus Mengudara: Aksi Terjun Payung Terunggul di Istana Merdeka - Media Indonesia
Watch the live action of Tijuana vs. Cruz Azul, all the latest news, analysis, and match scores...
Netizen tidak senang dengan komentar-komentar yang diberikan
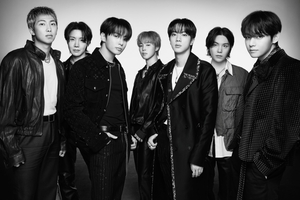
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...