


Former "Love and Hip Hop: Atlanta" Star Charged with Real Estate Fraud: What You Need to Know
Former cast member of "Love and Hip Hop: Atlanta" faces real estate fraud charges in Daytona Beach,...
The mortgage market is constantly evolving, influenced by a myriad of factors including economic indicators, monetary policy, and global events. As of June 18, 2026, the mortgage rates have experienced a notable decrease, with the 30-year fixed-rate mortgage hitting a one-month low. This decrease is a welcome change for potential homebuyers and those looking to refinance their current mortgages, as lower rates can lead to more affordable housing options.
One of the key factors influencing mortgage rates is the decision made by the Federal Reserve regarding interest rates. When the Fed lowers interest rates, it can lead to a decrease in mortgage rates, making borrowing cheaper for consumers. Conversely, an increase in interest rates by the Fed can cause mortgage rates to rise, making loans more expensive. Understanding the Federal Reserve's stance on interest rates is crucial for predicting the future of mortgage rates.
The impact of a one-month low in 30-year mortgage rates cannot be overstated. For homebuyers, this means potentially lower monthly payments, which can make the dream of homeownership more accessible. For those refinancing, lower rates can provide an opportunity to reduce their current mortgage payments or switch from an adjustable-rate to a fixed-rate loan, providing more stability in their financial planning.
Analyzing the implications of this trend, it's clear that the decrease in mortgage rates is a response to the current economic conditions. As the economy grows, there tends to be an increase in demand for housing, which can drive up prices and, consequently, mortgage rates. However, in periods of economic uncertainty or slower growth, interest rates, including those for mortgages, may decrease to incentivize borrowing and spending.
Looking forward, the outlook for mortgage rates is subject to a variety of factors. Economic indicators, such as inflation and unemployment rates, play a significant role in determining the direction of interest rates. Additionally, global events and monetary policy decisions by central banks around the world can influence U.S. mortgage rates. Predicting the future of mortgage rates with certainty is challenging, but understanding current trends and the factors that influence them can provide invaluable insights for making informed decisions.
The decrease in the 30-year mortgage rate to a one-month low as of June 18, 2026, is a significant development in the mortgage market. It reflects the dynamic nature of the economy and the mortgage industry's responsiveness to broader economic trends. For individuals planning to enter the housing market or refinance their existing mortgages, this decrease in rates presents an opportunity that should be carefully considered. With the right information and timing, potential homebuyers and refinancers can capitalize on these lower rates to achieve their financial goals.
In conclusion, the current state of mortgage rates, with the 30-year rate at a one-month low, is a critical piece of information for anyone involved in the housing market. Whether you're a first-time buyer, a seasoned homeowner, or an investor, understanding the factors that influence mortgage rates and how they impact your financial situation is essential. As the economic landscape continues to evolve, staying informed about the latest developments in mortgage rates will be crucial for making smart, well-timed decisions in the pursuit of homeownership or refinancing opportunities.
The current state of mortgage rates as of June 18, 2026, has seen a significant shift with the 30-year rate reaching a one-month low. This development is crucial for individuals looking to purchase or refinance a home, as it can substantially impact their monthly payments and overall cost of the loan.
Former cast member of "Love and Hip Hop: Atlanta" faces real estate fraud charges in Daytona Beach,...

A remarkable discovery of gold bars and coins worth an estimated $10 million was made by...

Reddit Stock Jumps on S&P 500 Inclusion Schaeffer's Investment Research
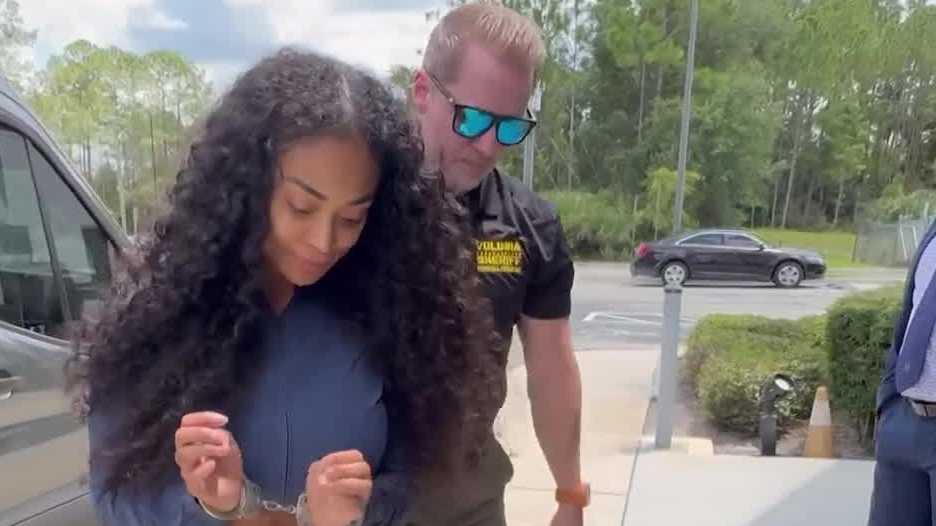
Reality TV star Salome Jackson arrested by Volusia deputies, linked to real estate fraud scheme.

Belgian Construction Workers Uncover a $10 Million Golden Surprise While Working on a Sewer System...
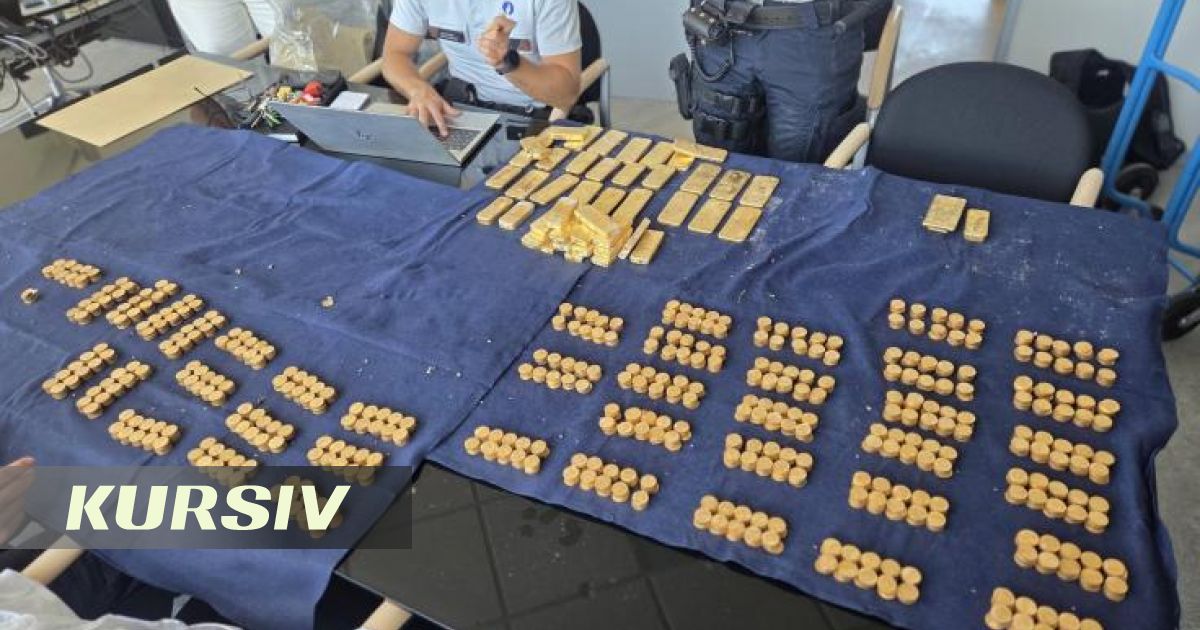
€9m gold treasure found hidden in Belgian building.
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...