
Bankruptcy Hits Rebel Creamery, a Low-Carb Ice Cream Brand Sold at Walmart and Target
Rebel Creamery, a popular low-carb ice cream brand sold at major retailers like Walmart and Target,...

The US stock market trimmed its gains on Wednesday as chip stocks sold off, despite strong earnings from chip equipment maker ASML and a softer-than-expected wholesale inflation reading. This unexpected turn of events has left many investors wondering what the future holds for the market. The Dow Jones Industrial Average and S&P 500 rose 0.1%, while the Nasdaq Composite rose 0.4% following gains from the day before. However, the semiconductor sector told a different story, with memory makers Micron Technology and SK Hynix tumbling 10% and 13%, respectively. This decline in semiconductor stocks has significant implications for the tech industry, which will likely be felt in the coming days and weeks.
On Wednesday morning, ASML raised its annual sales forecast above Wall Street forecasts, citing AI demand, and said it plans to increase its production capacity for chipmaking equipment by 30%. This move by ASML is a significant development in the semiconductor industry, as it indicates a strong demand for AI technology. The company's decision to increase production capacity is also a positive sign, as it will help meet the growing demand for chipmaking equipment. However, despite this positive news, chip stocks declined, with many investors selling off their shares. This sell-off is likely due to a combination of factors, including concerns over the global economy and the impact of trade tensions on the tech industry. As the market continues to evolve, it will be important to keep a close eye on the semiconductor sector and its potential implications for the broader market.
The economic data front also provided some insight into the current state of the market, with the Producer Price Index showing that wholesale inflation slowed more quickly than expected in June. This cooler-than-expected inflation reading is a positive sign, as it suggests that the economy is not overheating. The Consumer Price Index data also showed the largest single-month decline in inflation since April 2020, which is a significant development. However, this positive news was offset by rising oil prices, which have been a major concern for investors in recent weeks. President Trump's comments on Iran have also added to the uncertainty, as he stated that he would intensify attacks on the country until it relents. This geopolitical tensions have significant implications for the global economy, and will likely continue to impact the market in the coming days and weeks.
Earnings season continues to pick up, with Morgan Stanley, BlackRock, and Johnson & Johnson all reporting before the bell, while United Airlines Holdings will report after the close of the trading day. This earnings season has been highly anticipated, as investors look for insight into the current state of the market. The reports from these major companies will provide valuable information about the health of the economy and the potential implications for the market. As the earnings season continues, it will be important to keep a close eye on the reports from major companies, as they will provide significant insight into the current state of the market. The market's reaction to these reports will also be closely watched, as it will indicate the level of confidence that investors have in the economy.
The volatility in the market is also being driven by concerns over the global economy, particularly with regards to trade tensions and the impact of Brexit. The market is highly sensitive to any news or developments related to these issues, and any significant changes will likely have a major impact on the market. As the market continues to evolve, it will be important to keep a close eye on these developments, as they will have significant implications for the broader market. The market's reaction to these developments will also be closely watched, as it will indicate the level of confidence that investors have in the economy. In the coming days and weeks, it will be important to monitor the market's movements closely, as it will provide valuable insight into the current state of the economy and the potential implications for the market.
In conclusion, the stock market experienced a day of volatility, with the Dow, S&P 500, and Nasdaq seeing mixed results. The sell-off in semiconductor stocks, despite strong earnings from ASML and a softer-than-expected wholesale inflation reading, has significant implications for the tech industry. The economic data front provided some positive news, with the Producer Price Index showing that wholesale inflation slowed more quickly than expected in June. However, the market remains highly sensitive to any news or developments related to trade tensions and the impact of Brexit, and any significant changes will likely have a major impact on the market. As the market continues to evolve, it will be important to keep a close eye on these developments, as they will have significant implications for the broader market.
Looking ahead, the market is likely to remain highly volatile, with many investors closely watching the developments in the semiconductor sector and the broader economy. The earnings season will continue to provide valuable insight into the current state of the market, and the reports from major companies will be closely watched. The market's reaction to these reports will also be closely monitored, as it will indicate the level of confidence that investors have in the economy. As the market continues to evolve, it will be important to stay up-to-date with the latest developments and to closely monitor the market's movements. With the current level of uncertainty and volatility in the market, it is more important than ever to stay informed and to be prepared for any potential changes in the market.
The stock market experienced a day of volatility as the Dow, S&P 500, and Nasdaq saw mixed results, with semiconductor stocks selling off despite strong earnings from ASML and a softer-than-expected wholesale inflation reading.
Rebel Creamery, a popular low-carb ice cream brand sold at major retailers like Walmart and Target,...
Marseille's Owner Injects €50.2 Million into the Football Club: A Strategic Move to Secure the...
Rebel Creamery LLC, a major ice cream brand, has filed for Chapter 11 bankruptcy following a...
Major ice cream brand seeks Chapter 11 bankruptcy after lawsuit
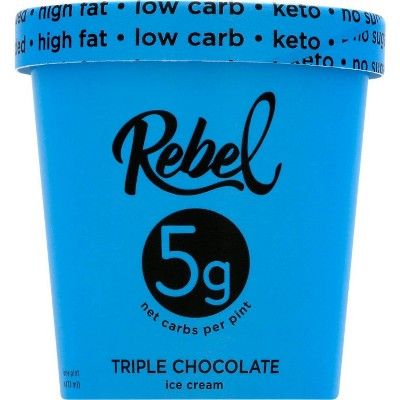
Ice cream brand sold in Houston faces financial repercussions after losing a high-profile lawsuit...

Ice Cream Maker Rebel Creamery Files for Bankruptcy After Being Ordered to Pay $23.8 Million in...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...