

Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru
Nvidia's quarterly data center revenue has eclipsed its competitor AMD's by more than 13x, with the company's networking silicon being flagged as the next big thing by analysts at Bank of America. The networking segment has tripled to $14.8 billion in a year, yet the market still prices Nvidia's shares as a pure compute play, leaving 23% upside to a $261 target. This significant growth potential is largely driven by the increasing demand for AI-powered computing solutions, which are being adopted rapidly across various industries.
Bank of America's analysts have highlighted the enormous scale of the opportunity in Nvidia's networking segment, with the company's quarterly data center revenue being a key driver of growth. The analysts have also pointed out that Broadcom's surging $10.8 billion AI networking segment validates the opportunity's enormous scale. This underscores the potential for Nvidia's networking segment to become a significant contributor to the company's revenue in the coming years.
Nvidia has been investing heavily in its data center business, with its quarterly data center revenue growing at a compound annual growth rate (CAGR) of 199%. This growth is being driven by the increasing adoption of AI-powered computing solutions by hyperscalers, which are investing heavily in building out their data centers to cater to the growing demand for cloud services. Nvidia's networking silicon is at the heart of this growth, providing the necessary computing power for AI workloads.
The bull case for Nvidia's networking segment rests on three key levers: networking scaled from roughly $7.25 billion in Q2 FY26 to $14.8 billion last quarter; supply commitments hit $119 billion, up from $50.3 billion two quarters ago; and capital return: an $80 billion buyback authorization landed in May on top of the $38.5 billion remaining. These levers are expected to drive Nvidia's networking segment to a $20 billion business in the coming years, providing significant upside to the company's revenue and profitability.
However, there are also risks associated with Nvidia's networking segment, including the potential for a sustained hyperscaler capex reset and a prolonged export freeze. Any weakness in the data center market could impact Nvidia's networking segment, resulting in decreased revenue and profitability. Nevertheless, based on Bank of America's analysis, the risks appear to be manageable, and the potential upside for Nvidia's networking segment remains significant.
Jensen Huang, Nvidia's CEO, has stated that the buildout of AI factories, the largest infrastructure expansion in human history, is accelerating at an extraordinary speed. This underscores the growing importance of AI-powered computing solutions and the potential for Nvidia's networking segment to become a significant contributor to the company's revenue in the coming years.
Based on Bank of America's analysis, the current market valuation of Nvidia's shares appears to be undervalued. The analysts have set a price target of $261 for Nvidia's shares, implying 23.28% upside from the current share price. This target price is based on the expected growth potential of Nvidia's networking segment and the company's overall performance in the coming years.
However, it's worth noting that Nvidia's shares have historically been volatile, and the company's performance has been affected by various factors, including changes in market trends and the company's own execution. Nevertheless, based on Bank of America's analysis, the potential upside for Nvidia's shares appears to be significant, and investors may want to consider adding the company to their portfolio.
Contact [email protected] for any questions or corrections.
The setup looks constructive if hyperscaler capex guides stay firm through the next TSMC report. However, if China export policy tightens further and Q2 revenue prints below the $91 billion guide, the thesis may weaken. Nevertheless, based on current trends and Nvidia's performance in the past, the risks appear to be manageable, and the potential upside for the company's shares remains significant.
The bull case for Nvidia's networking segment is based on strong fundamental growth, driven by the increasing demand for AI-powered computing solutions and the company's leadership position in the data center market. Analysts at Bank of America believe that Nvidia's networking segment has the potential to become a multi-billion-dollar business in the coming years, providing significant upside to the company's revenue and profitability.
While there are risks associated with Nvidia's networking segment, including the potential for a sustained hyperscaler capex reset and a prolonged export freeze, the company's leadership position in the data center market and its strong fundamental growth drivers are expected to drive the segment's growth in the coming years. Based on this analysis, investors may want to consider adding Nvidia to their portfolio, with a target price of $261 based on expected growth potential.
Bank of America sees Nvidia's networking segment as a multi-billion-dollar opportunity. Here's why NVDA stock could reach new heights.
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru

Acara 600 ribu porsi kulinier gratis di Monas, menghidupkan semangat kebangsaan dan memperkuat rasa...
Hayden Panettiere, bintang televisi Amerika yang terkenal dengan perannya dalam serial 'Heroes' dan...
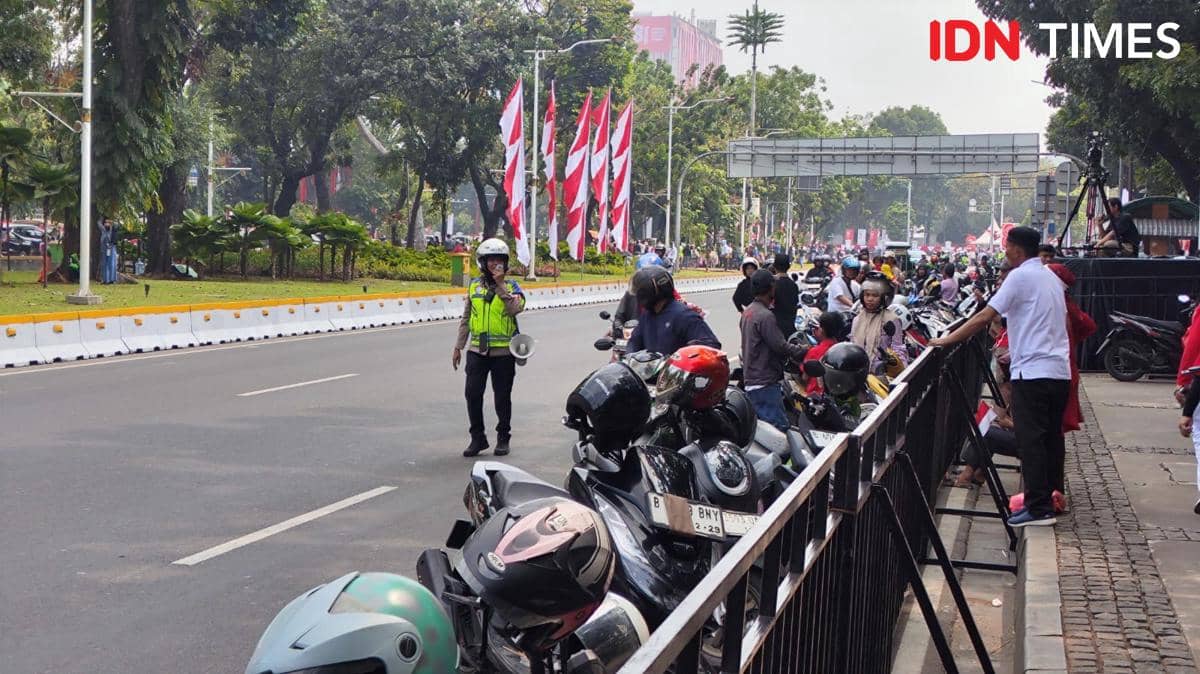
Jalan Merdeka Barat Dekat Istana Merdeka Jadi Parkir Liar Warga yang ke Monumen Nasional IDN Times

Kopassus Mengudara: Aksi Terjun Payung Terunggul di Istana Merdeka - Media Indonesia
Watch the live action of Tijuana vs. Cruz Azul, all the latest news, analysis, and match scores...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...