

Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru
Micron's stunning Q3 2026 earnings, with revenue and earnings significantly beating analyst estimates and a roughly 7x share price move over the past year, has brought fresh attention to companies that power data centers and advanced computing. When one stock in the ecosystem reports very strong numbers, investors often start asking which other large, higher quality stocks could be exposed to the same AI-driven demand story, or which might be left behind. This article looks at 3 stocks from an AI data center infrastructure screener that appear positively linked to the news around Micron's latest results, providing a deeper look into the AI-driven software landscape and its growing importance in the tech industry.
Overview: Five9 provides cloud-based contact center software that uses AI agents, automation, and integrations with tools like CRM systems to help businesses manage customer interactions across voice, chat, email, web, social, and mobile channels. The company's software is designed to help organizations streamline their customer service operations, improve efficiency, and enhance the overall customer experience.
Operations: Five9 generates about US$1.17 billion in revenue from Internet Software & Services, with roughly US$1.04 billion coming from the United States and US$134.77 million from international markets. The company's revenue growth is driven by its expanding customer base, increasing demand for cloud-based contact center solutions, and its strategic partnerships with leading technology companies.
At the intersection of the AI data center build-out and customer experience, Five9 uses AI agents, workflow automation, and partnerships with platforms like Salesforce and Google Cloud to turn data center capacity into higher-value customer interactions. Recent transcripts highlight enterprise AI bookings growth, expanding margins, and free cash flow, while buybacks and governance changes indicate a company actively reshaping itself.
However, investors need to weigh intensifying competition, leadership changes, and the use of external borrowing against the appeal of a scalable, subscription-heavy model. For investors following Micron's AI-driven performance, Five9 offers a different but closely connected way to think about how that spending filters through to software and recurring revenue.
Additionally, Five9's AI contact center story is gaining attention, but the real tension is how scalable growth, margin trends, and cash generation stack up against competition, debt, and buybacks, which makes the 4 key rewards and 3 important warning signs feel especially important. This raises one uncomfortable question investors rarely ask: how does Five9's growth strategy align with its financial performance, and what are the implications for its investors?
Overview: Atlassian is a software company that helps teams plan projects, track work, share knowledge, and manage support requests through tools like Jira, Confluence, Trello, and newer AI products such as Rovo and Loom. The company's software is designed to keep technical and non-technical teams aligned in one system of work, improving collaboration, productivity, and overall team performance.
Operations: Atlassian generates about US$6.19 billion in revenue from Software & Programming, with customers spread across the United States, EMEA, Asia Pacific, and the rest of the Americas. The company's revenue growth is driven by its expanding customer base, increasing demand for cloud-based collaboration tools, and its strategic partnerships with leading technology companies.
Atlassian sits in the slipstream of Micron's AI data center developments because its cloud tools and AI assistant Rovo depend on the kind of high-performance infrastructure that large enterprises are now locking in for years. Recent results show revenue of US$1.8 billion in Q3 with strong cloud and remaining performance obligations, plus growing usage of AI features, while the stock trades below one estimate of fair value on P/S and analysts still model earnings growth and a path to profitability.
However, Atlassian is currently loss-making, carries higher risk funding, and has a volatile share price. This makes its mix of AI exposure and execution risk a story worth studying in far more detail before forming an investment view. The key rewards and 2 important warning signs of Atlassian's AI story suggest a nuanced perspective is required to navigate its growth, risks, and valuation.
Overview: Vertex provides enterprise tax software that helps large retailers, wholesalers, and manufacturers calculate indirect taxes on transactions, manage e-invoicing, and compliance, and connect into systems like SAP so global companies can keep up with complex, frequently changing tax rules.
Operations: Vertex generates about US$768.0 million in revenue from Software & Programming, with roughly US$685.7 million from the United States and US$82.3 million from international markets. The company's revenue growth is driven by its expanding customer base, increasing demand for cloud-based tax solutions, and its strategic partnerships with leading technology companies.
Vertex sits in the slipstream of Micron's AI-fueled data center boom because its SaaS tax engines and e-invoicing tools run at the same scale as those global infrastructure investments, turning rising digital transaction volumes into recurring compliance revenue. Investors get a company that management says is seeing margin leverage from higher cloud mix, plus solid retention metrics and AI enhancements that aim to automate more of the tax workflow.
The stock trades at a P/S below both peers and one estimate of fair value on sales, but Vertex is currently loss-making, operates with higher risk external funding, and faces intense competition. This makes a closer look at how its growth, risks, and valuation fit together especially important now, with 3 key rewards and 2 important warning signs raising questions about Vertex's overall attractiveness.
The three stocks in this article are just a starting point, and the full AI Data Center Infrastructure screener surfaces 18 more companies with equally compelling AI data center infrastructure narratives that many investors have not yet looked at closely. Use Simply Wall St to identify and analyze the exact catalysts, quality metrics, and business models that matter to you, so you can focus on the highest conviction AI data center infrastructure ideas.
Micron's Earnings are Shifting Investor Attention to AI-Focused Software Stocks simplywall.st
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru

Acara 600 ribu porsi kulinier gratis di Monas, menghidupkan semangat kebangsaan dan memperkuat rasa...
Hayden Panettiere, bintang televisi Amerika yang terkenal dengan perannya dalam serial 'Heroes' dan...
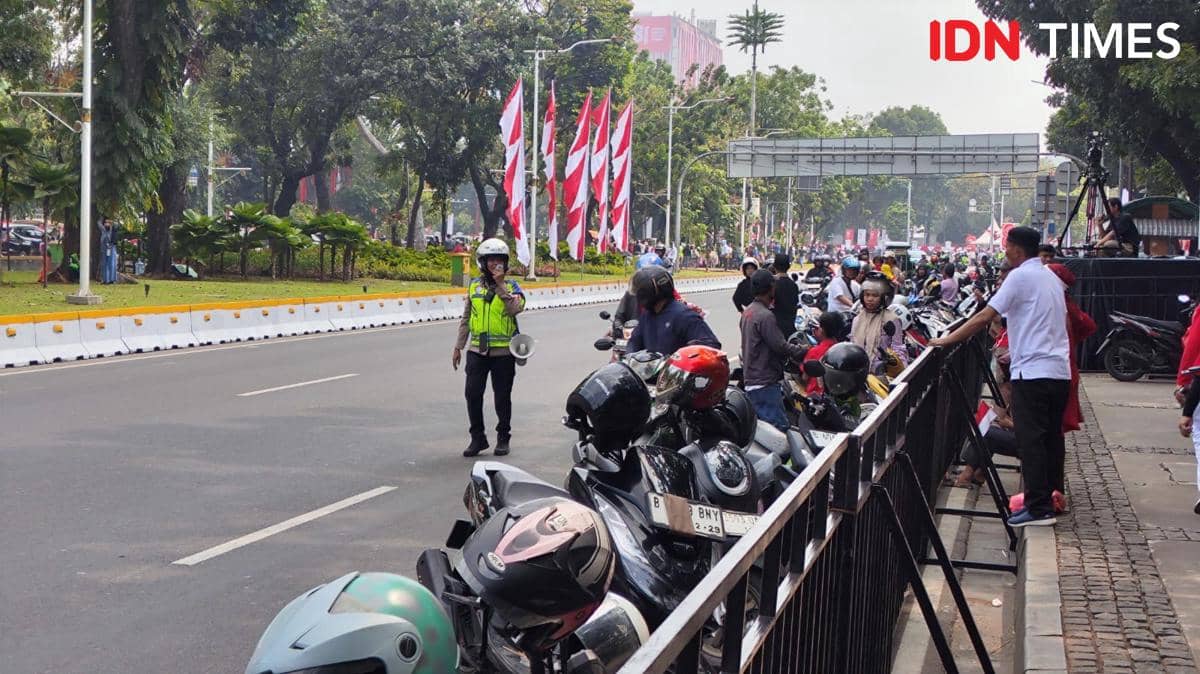
Jalan Merdeka Barat Dekat Istana Merdeka Jadi Parkir Liar Warga yang ke Monumen Nasional IDN Times

Kopassus Mengudara: Aksi Terjun Payung Terunggul di Istana Merdeka - Media Indonesia
Watch the live action of Tijuana vs. Cruz Azul, all the latest news, analysis, and match scores...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...