
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru
According to the latest mortgage market trends, some mortgage offers are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure. Mortgage interest rates have been a topic of discussion among economists, policymakers, and homebuyers in recent times. The current state of mortgage rates is a mixed bag, with the 30-year fixed rate experiencing a slight uptick, while remaining the lowest 30-year rate since May 12. Meanwhile, the 15-year fixed loan has seen a 5 basis point drop, and the 5/1 ARM has decreased by 3 basis points. This phenomenon is a reflection of the ongoing fluctuations in the mortgage market, influenced by various economic factors and government policies.
As of Tuesday, June 30, 2026, the average 30-year fixed mortgage rate stands at 6.19%, representing a 2 basis point increase from the previous day. Notwithstanding this slight uptick, the current rate remains the lowest 30-year rate observed since May 12. The 15-year fixed loan is currently priced at 5.70%, representing a 5 basis point decrease compared to the previous day. In contrast, the 5/1 ARM has dropped to 6.06%, a 3 basis point decrease from Monday. These variations in mortgage rates underscore the dynamic nature of the mortgage market, which is subject to a multitude of factors, including economic trends, government policies, and market sentiment.
When delving into the specifics, the weekly survey of mortgage lenders reveals that rates have become more favorable, with 6% now being a feasible option (without fees). This development is attributed to the recent drop in interest rates, which has made it more affordable for homebuyers to secure a mortgage. As a result, more homebuyers are opting for fixed-rate mortgages, which offer predictability and stability in their monthly payments. Nevertheless, it is essential to note that mortgage rates can fluctuate rapidly, and homebuyers should be prepared for potential changes in the market.
The current mortgage rates are as follows, according to our latest Zillow data, for Tuesday, June 30, 2026:
It is essential to remember that these rates are national averages and are rounded to the nearest hundredth. Additionally, refinance rates are generally higher than purchase rates. Given this, homebuyers should carefully consider their financial situation and long-term goals before making a decision. As rates can change frequently, it is vital to stay informed and adjust your strategy accordingly.
A mortgage calculator can be a valuable tool in determining how various mortgage terms and interest rates will impact your monthly payments. By using this calculator, you can explore different scenarios and find the most suitable option for your financial situation. This can be particularly useful when considering factors such as property taxes and homeowners insurance, which can significantly affect your total monthly payment.
When comparing 15- versus 30-year mortgage rates, it is essential to note that the shorter term will result in lower interest payments over the life of the loan. However, your monthly payments will be higher because you are paying off the same loan amount in half the time. For instance, with a $400,000 mortgage with a 30-year term and a 6.19% rate, your monthly payment would be approximately $2,447.28 toward your mortgage principal and interest. As interest accumulates over decades, you would end up paying $481,021 in interest.
On the other hand, a $400,000 15-year mortgage with a 5.65% rate would result in a monthly payment of around $3,300.26 toward your principal and interest. In this scenario, you would only pay $194,047 in interest over the years. This highlights the importance of considering your financial situation and goals when choosing a mortgage term. If you find the 15-year payment option too high, you can always make extra payments on your 30-year loan to pay it off faster and reduce interest payments in the long run.
It is also worth noting that with a fixed-rate mortgage, your rate is locked in from day one. However, you would receive a new rate if you refinance your mortgage. In contrast, an adjustable-rate mortgage keeps your rate the same for a specified period, before adjusting annually according to various factors, such as the economy. This type of mortgage can sometimes offer lower interest rates upfront, but it carries a risk of higher rates after the initial rate-lock period expires.
The future outlook for mortgage rates appears uncertain, with forecasts indicating a potential increase in rates over the next few years. According to the Mortgage Bankers Association (MBA), the 30-year mortgage rate is expected to be around 6.50% through 2026, while Fannie Mae predicts an average rate of 6.4% for the rest of the year. As a result, homebuyers may want to consider locking in a mortgage rate as soon as possible to avoid potential rate increases. Furthermore, with refinance rates currently below 5%, now may be an opportune time to refinance your mortgage loan and save on interest payments.
Mortgage rates are predicted to remain relatively stable in 2027, with the MBA forecasting 30-year fixed rates of 6.5% for the entire year. Fannie Mae, on the other hand, expects average rates to hold near 6.3% for most of 2027. Given these predictions, homebuyers should remain cautious and continue to monitor market trends to make informed decisions about their mortgage options.
Mortgage and refinance interest rates today, Tuesday, June 30, 2026: Rates mixed, but lowest 30-year rate since May
Pemerintah Kabupaten Aceh Tamiang: Bumi Muda Sedia Pulih dan Bangkit — Informasi Terbaru

Acara 600 ribu porsi kulinier gratis di Monas, menghidupkan semangat kebangsaan dan memperkuat rasa...
Hayden Panettiere, bintang televisi Amerika yang terkenal dengan perannya dalam serial 'Heroes' dan...
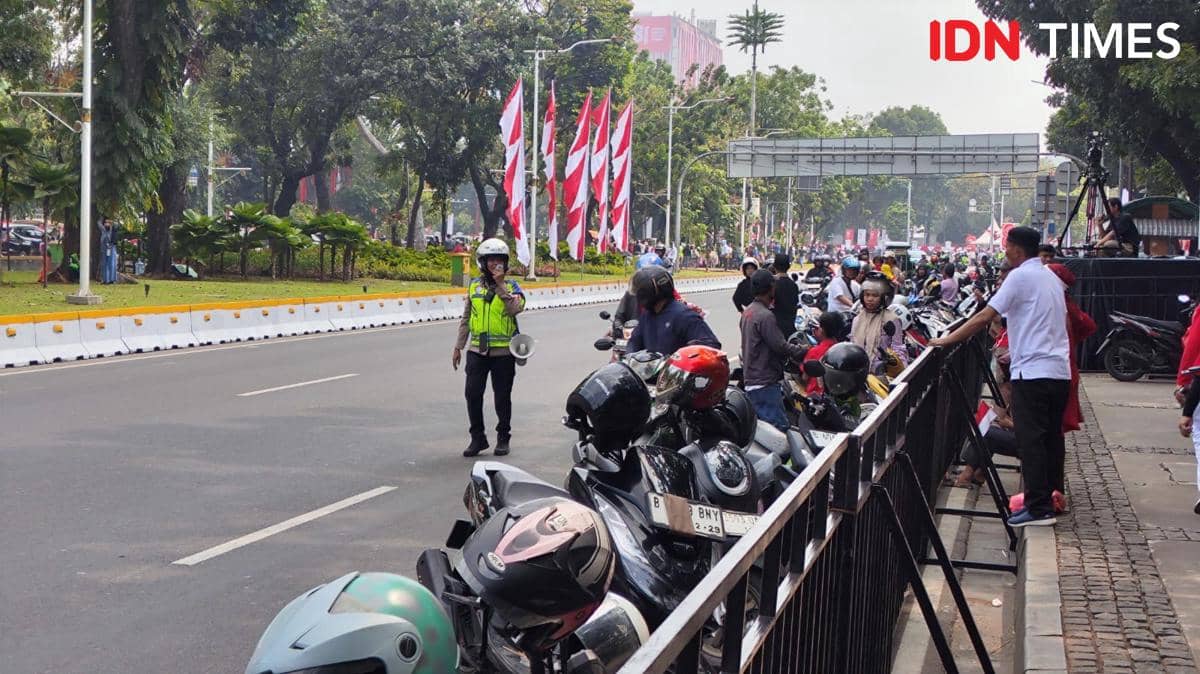
Jalan Merdeka Barat Dekat Istana Merdeka Jadi Parkir Liar Warga yang ke Monumen Nasional IDN Times

Kopassus Mengudara: Aksi Terjun Payung Terunggul di Istana Merdeka - Media Indonesia
Watch the live action of Tijuana vs. Cruz Azul, all the latest news, analysis, and match scores...
Netizen tidak senang dengan komentar-komentar yang diberikan
BTS mungkin kembali mengikuti Grammy setelah rekanan mereka, Recording Academy, mengumumkan revisi...
BTS mungkin tidak akan mengubah keputusan untuk mengabaikan Grammy karena deadline pengiriman musik...
Update terbaru tentang keputusan BTS untuk tidak mengirimkan musik mereka untuk dijadikan nominee...
Pihak Recording Academy mengumumkan akan kembali meninju keputusan untuk memperkenalkan kategori...
Sangyeop Sangyeop mengumumkan rencananya untuk menikah dengan seorang non-celebrity, mengejutkan...